A back brace can have three very different prices attached to it: the supplier’s cash price, the amount the supplier bills Medicare, and the amount Medicare actually approves. The largest number on the paperwork is therefore not automatically the number Medicare pays or the amount you owe.
For people with Original Medicare, the comparison usually comes down to this: compare the all-in cash price with your expected responsibility based on the Medicare-approved amount, not with the supplier’s billed charge. Your remaining Part B deductible, the supplier’s Medicare status, assignment, the exact brace code, and coverage requirements can completely change the result.
Medicare Part B covers medically necessary arm, leg, back, and neck braces when they meet Medicare requirements and are ordered by a doctor or other qualified health care provider. Medicare’s official brace coverage guidance says beneficiaries generally pay 20% of the Medicare-approved amount after the Part B deductible.
Table of Contents
Cash price, billed charge, and Medicare-approved amount are different numbers
The easiest way to understand a back-brace bill is to stop thinking of it as having one price.
| Number | What it means | Does it determine what you pay? |
|---|---|---|
| Cash or self-pay price | The price offered if you pay directly under the supplier’s self-pay arrangement | Yes, if that is the payment route you actually use |
| Supplier billed charge | The amount placed on the Medicare claim | Not necessarily |
| Medicare-approved amount | The amount Medicare recognizes under its payment rules | Usually the key number for an assigned Original Medicare claim |
| Your patient responsibility | Deductible, coinsurance, and potentially noncovered amounts | This is the number that matters to your wallet |
CMS explains that most DMEPOS items, which include orthotics such as back braces, are paid under fee-schedule rules. In general, Medicare payment is calculated using the lower of the supplier’s actual charge or the applicable fee-schedule amount. You can review the methodology on the CMS DMEPOS payment policy page.
This is why a claim showing a $500 charge does not necessarily mean Medicare considers the brace to be worth $500. The approved amount might be substantially different.
If terms such as billed charge, allowed amount, deductible, and coinsurance are blurring together, this guide to orthopedic billing terms explains how those numbers fit together before you compare prices.
How Original Medicare calculates your back-brace cost
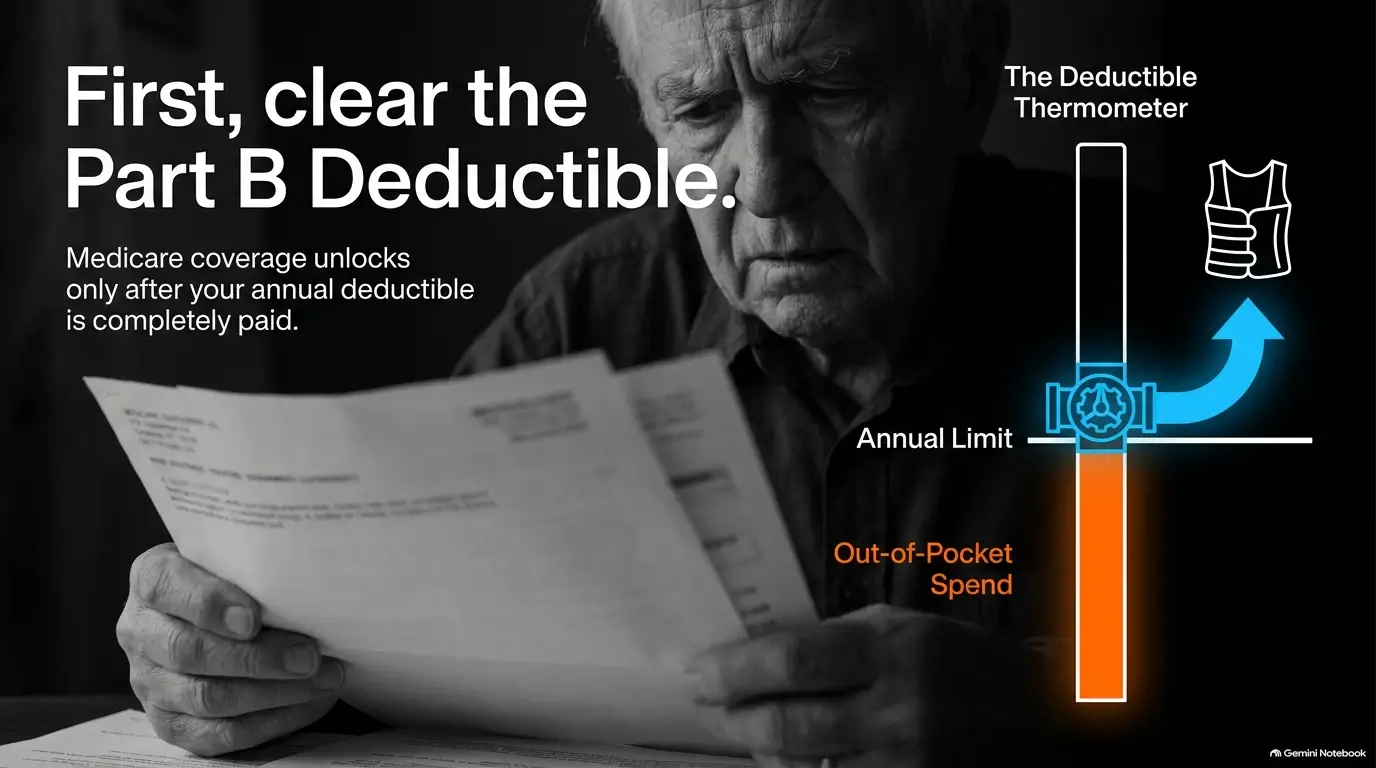
When a covered back brace is obtained from an appropriate Medicare supplier that accepts assignment, the usual Original Medicare structure is straightforward: the Part B deductible applies first, and Medicare generally pays 80% of the approved amount remaining after the deductible. You are generally responsible for 20%.
For calendar year 2026, the annual Medicare Part B deductible is $283. CMS publishes the amount annually, so readers comparing costs in a later year should check the current figure rather than relying on an older estimate.
Example 1: Your deductible has already been met
Suppose a supplier gives you these numbers:
- Cash price: $125
- Supplier billed charge to Medicare: $450
- Medicare-approved amount: $240
- Remaining Part B deductible: $0
If the claim is covered and the supplier accepts assignment, your 20% coinsurance would be $48. Medicare would generally pay the remaining $192.
In this hypothetical example, using Medicare costs you $48 rather than the $125 cash price. The $450 billed charge is mostly noise from the patient’s perspective because it is not the amount used to calculate the assigned claim.
Example 2: You still have your deductible remaining
Now use the same $240 Medicare-approved amount, but assume you still have at least $240 of your Part B deductible remaining.
The entire $240 could be applied to your deductible. In that situation, the $125 cash price looks considerably cheaper than paying $240 through the Medicare claim.
But that does not automatically mean you should pay cash. You also need to determine whether the supplier can treat the transaction as self-pay, whether a Medicare claim will be submitted, whether any Medicare notice is required, and what happens to your deductible if no claim is processed.
Why a cheap cash price can sometimes beat Medicare
Insurance usually sounds like the cheaper route, but a deductible can turn that intuition upside down.
If you have a large amount of your Part B deductible remaining and the supplier offers a genuinely low all-inclusive self-pay price, the immediate cash cost may be lower than your Medicare responsibility.
That comparison is most useful when you know all of the following numbers before accepting the brace:
- The exact cash price
- The HCPCS code the supplier expects to bill
- The estimated Medicare-approved amount
- Your remaining Part B deductible
- Your expected coinsurance
- Any fitting, adjustment, accessory, or upgrade charges
A vague statement such as “Medicare covers it” is not enough. A $240 covered claim and a $125 cash purchase can produce very different results depending on how much deductible remains.
Why using Medicare can still be cheaper than the cash price
Once your Part B deductible has been satisfied, Medicare billing can become much more attractive. If the approved amount is $240, for example, 20% coinsurance is only $48 when assignment and normal coverage rules apply.
Using Medicare may also preserve a formal claim record. That can matter if the claim is denied and you need to understand or challenge the decision later. If you encounter a denial, this guide to a denied brace insurance appeal explains how to organize the order, claim, denial reason, and supporting medical documentation.
Before comparing prices, confirm that the back brace qualifies for Medicare coverage
A low coinsurance percentage is irrelevant if the brace does not satisfy Medicare’s coverage rules.
CMS treats back braces as spinal orthoses. Under the current Medicare spinal orthosis coverage policy, covered spinal orthoses can include devices ordered to restrict trunk movement to reduce pain, support healing after spinal or related soft-tissue injury, support healing after spinal surgery, or support weak spinal muscles or a deformed spine.
A soft support purchased from a retail shelf for general comfort should therefore not be assumed to qualify simply because the package calls it a “back brace.” Medicare billing depends on the actual orthosis, its HCPCS code, the medical reason for it, and the supporting documentation.
Before delivery, ask the supplier for the expected HCPCS code. If you want a broader pre-purchase checklist, see this guide to checking orthopedic brace insurance coverage.
Some back braces have additional Medicare requirements
Some spinal orthosis codes are subject to additional Medicare conditions such as a qualifying face-to-face encounter, a written order before delivery, or prior authorization. The requirements are code-specific and can change.
CMS advises suppliers that Medicare DMEPOS claims require appropriate orders and supporting documentation, and certain items have additional pre-delivery requirements. Check the current CMS DMEPOS order requirements before assuming that a prescription alone is enough.
This distinction is especially important when the cash option is available immediately but the Medicare route is still waiting for paperwork. Taking the brace home before a required authorization or order is completed can change the billing outcome.
Supplier assignment can matter as much as the brace price
Before accepting a brace under Original Medicare, ask whether the supplier is enrolled in Medicare and whether it accepts assignment for the item.
A participating Medicare supplier must accept assignment. That generally means the supplier accepts the Medicare-approved amount as full payment for the covered item, apart from your deductible and coinsurance.
A nonparticipating supplier may accept assignment on an individual claim but is not necessarily required to do so. Medicare warns that you may pay more when a supplier does not accept assignment.
You can use Medicare’s medical equipment supplier search to look for Medicare suppliers in your area, but it is still sensible to confirm assignment directly with the supplier for the particular transaction.
Do not assume you can simply tell the supplier, “I’ll pay cash instead”
Cash payment becomes more complicated when an item might otherwise be covered by Medicare.
Ask the supplier specifically whether it intends to submit a Medicare claim. If Medicare may deny the item, the supplier may also discuss an Advance Beneficiary Notice of Noncoverage, commonly called an ABN. Depending on the circumstances and the option selected on the notice, the beneficiary may be accepting financial responsibility and may be asked whether a claim should be submitted.
The practical point is simple: do not assume that paying cash at the counter automatically creates a Medicare reimbursement right later. Likewise, do not assume a payment made entirely outside a Medicare claim will automatically be credited toward your Part B deductible.
Before paying, ask the supplier to put the arrangement in writing.
The nine questions to ask before buying the brace
- What is the exact make and model of the back brace?
- What HCPCS code or codes will you bill?
- What is your complete cash price, including fitting and adjustments?
- Are you enrolled as a Medicare supplier?
- Will you accept assignment for this brace?
- What Medicare-approved amount do you expect for this code in my area?
- Does this brace require prior authorization, a face-to-face encounter, or a written order before delivery?
- What will my estimated responsibility be after my remaining Part B deductible?
- If I choose the cash price, will you submit a Medicare claim, and what Medicare paperwork applies?
Write down the answers rather than relying on a verbal quote. Keep the order, HCPCS code, supplier name, price quote, authorization information, receipt, claim, and Medicare Summary Notice together until the claim is resolved.
What if you have Medicare Advantage instead?
The calculations above are primarily about Original Medicare.
Medicare Advantage plans must cover medically necessary services that Original Medicare covers, but the plan can have its own provider networks, cost-sharing structure, and prior-authorization procedures. The supplier that works for an Original Medicare beneficiary may not be the supplier your Medicare Advantage plan wants you to use.
If you have Part C, compare the cash price with the amount your specific plan says you will owe rather than automatically applying the Original Medicare 20% calculation. This guide to Medicare Advantage orthopedic care explains the network and authorization issues that can change the comparison.
Cash price vs Medicare billing: a practical comparison
| Situation | What may deserve closer attention |
|---|---|
| Your Part B deductible is already met | Medicare coinsurance may be substantially below the cash price |
| Most of your deductible remains | A low cash price may be less than your immediate Medicare responsibility |
| The supplier accepts assignment | Your covered cost is tied to the Medicare-approved amount rather than simply the billed charge |
| The supplier does not accept assignment | Ask for a written estimate because your costs may be higher |
| The brace requires prior authorization or special documentation | Do not compare prices until eligibility and paperwork are checked |
| You have Medicare Advantage | Use your plan’s network, authorization, and cost-sharing rules instead of assuming Original Medicare pricing |
The number to compare is your final expected cost
A $450 Medicare claim is not automatically more expensive than a $125 cash brace. If Medicare approves $240 and your deductible is already met, your assigned-claim responsibility could be only $48. Conversely, if the entire approved amount falls under your remaining deductible, the $125 cash option could look cheaper at the register.
The useful comparison is therefore not cash price versus billed charge. It is cash price versus expected Medicare patient responsibility.
Get the HCPCS code, confirm medical-necessity and documentation requirements, verify the supplier’s Medicare enrollment and assignment status, check your remaining deductible, and ask what happens to the Medicare claim if you choose self-pay. Those few questions turn two confusing price tags into a comparison you can actually use.